News
July 15, 2026
Europe is entering a new phase of digital payments. For years, the European payments market has been dominated by cards, but today that infrastructure is changing. The question is: how do we turn it into a payment experience that merchants and consumers actually want to use?
The EU has been actively developing the infrastructure and regulation needed to make instant payments more accessible.
Since October 2025, payment service providers in the EEA have been required to let customers send instant euro payments and verify the payee. This allows euro payments to be sent 24/7 and reach recipients within seconds.
But faster bank transfers alone do not automatically create a better payment experience.
This is where Pay-by-Bank becomes particularly interesting.
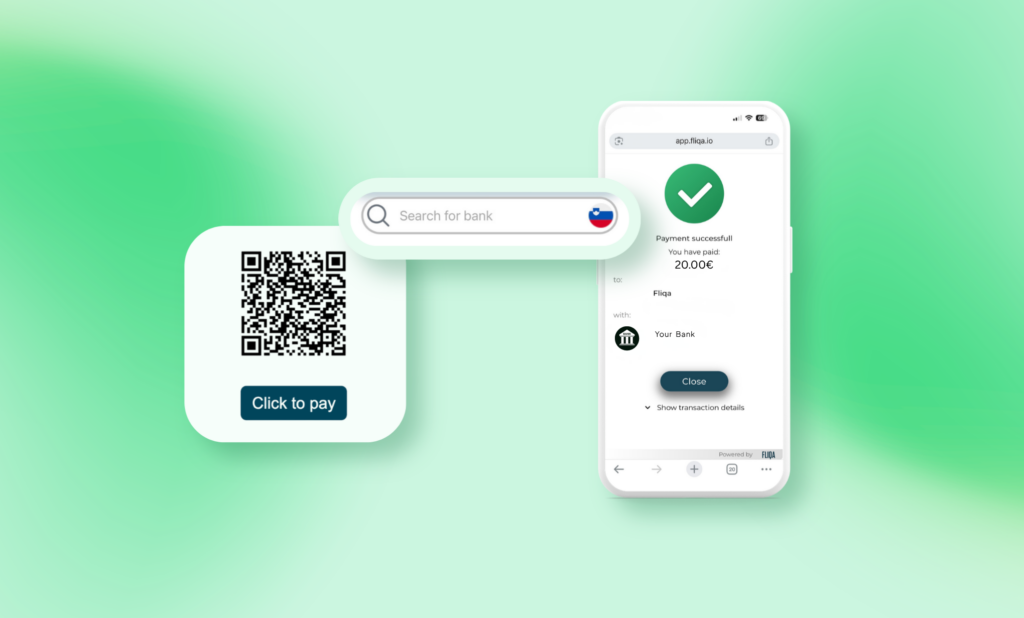
Instant payments describe how quickly money can move between bank accounts. Pay-by-Bank describes the customer-facing experience that allows someone to initiate that payment directly from their bank account at checkout.
Open Banking connects the customer, their bank, and the payment provider. Instant payment infrastructure provides the speed behind the transaction.
Together, these technologies create the foundation for a different way of paying online.
The ECB’s 2026 payments strategy highlights pan-European retail payment solutions based on instant payments as an important part of building a more competitive, resilient and autonomous European payments ecosystem.
For merchants, the shift towards account-to-account payments is about more than new technology.
Pay-by-Bank can help businesses reduce payment processing costs, access funds faster and reduce exposure to the traditional card chargeback mechanism. It also gives customers another way to pay without entering card details.
Merchants can now choose between different payment methods depending on their customers, markets, and business needs.
Europe has made significant progress in building the infrastructure for instant payments. Now comes the harder part: adoption. Because better infrastructure only matters if people actually use it.
For consumers, Pay-by-Bank needs to be simple, secure, and convenient. For merchants, it needs to be commercially viable and easy to integrate.
That is where payment providers play an important role.
FLIQA enables merchants to accept Pay-by-Bank payments through Open Banking, connecting customers and businesses through direct bank payments.
Our goal is to make account-to-account payments a practical option for businesses looking to reduce costs, improve cash flow, and offer customers another secure way to pay.
As instant payments become increasingly embedded in European financial infrastructure, the next stage will be turning that infrastructure into everyday payment experiences.